
1. Interest or dollars?
Turkish savers have argued about the same question for decades: keep the money in a lira time deposit and collect the interest, or convert it to dollars and hold. The dilemma is common enough to have a household name — faiz mi, dolar mı?, “interest or dollars?” Both answers have had long stretches of looking right, which is why the argument never ends.
Figure 1 settles it the only way it can be settled: by measuring both strategies in the only unit that matters to a saver, purchasing power. Start in January 2013 with one lira of spending power. One saver keeps the money in a lira deposit and renews it at the going rate, forever. The other converts to dollars and sits in short-term US Treasuries. Thirteen and a half years later, the deposit account buys 1.1× what it did in 2013 — essentially nothing gained — and along the way, between 2021 and 2023, it lost about half of its purchasing power while rates were held far below inflation. The dollar position ends better, at 1.6×, but since the policy turn of mid-2023 it has been losing roughly 10 percent of purchasing power per year: with Turkish interest rates held high against inflation, the lira has been appreciating in real terms, while dollars pay four or five percent nominal. Note that this is the generous version of the dollar strategy — it is credited with the Treasury yield, which most retail dollar-holders never actually collect. Banknotes in a drawer, the more common practice, end near 1.4× and are currently losing about 13 percent a year.
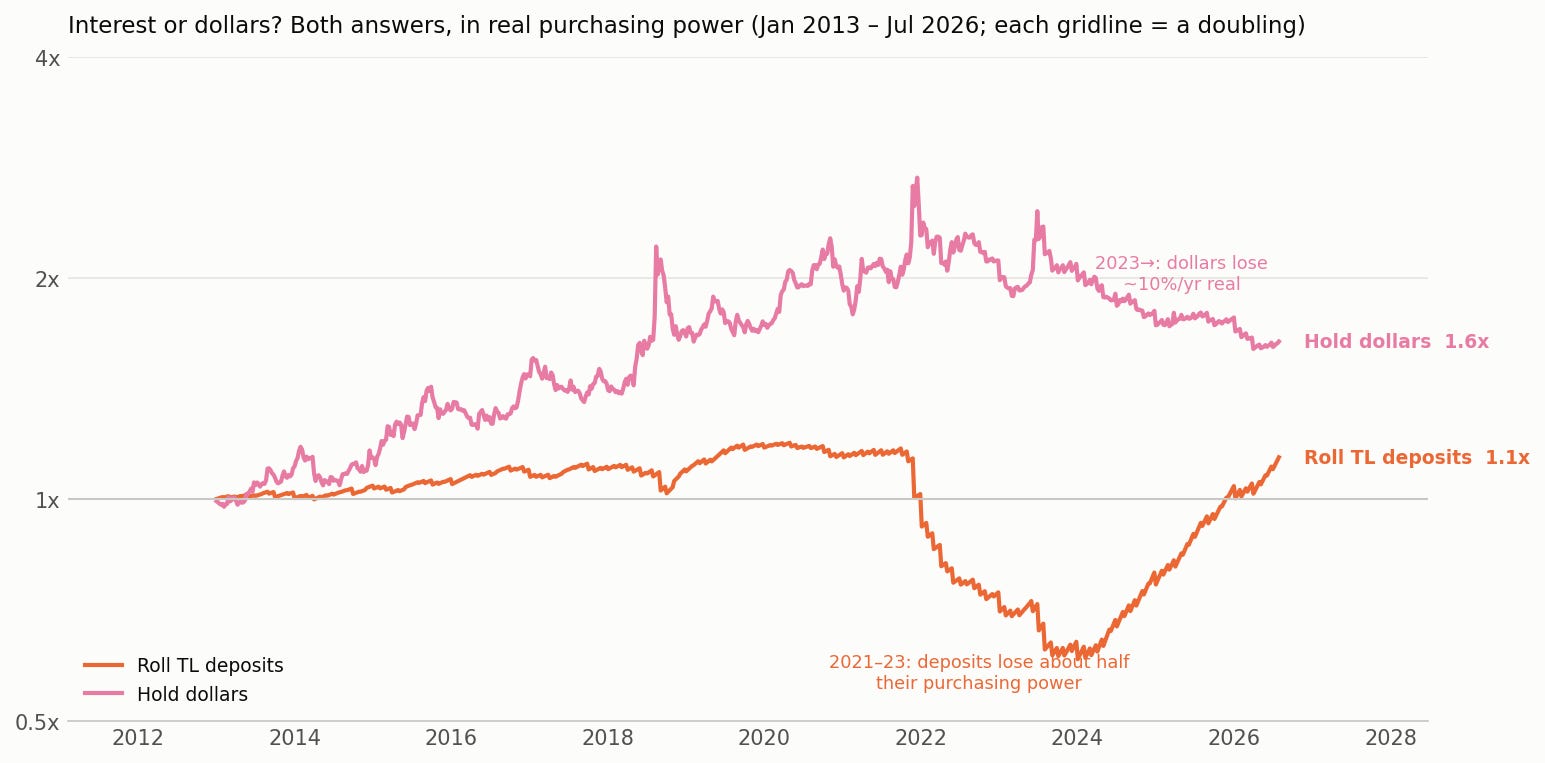
Both answers had a regime that punished them severely. The question is unanswerable as posed: it assumes there is a single safe asset, and in Turkey there is none.
2. The other choices are no better
Widen the comparison to everything a Turkish retail investor actually reaches for, and the picture barely improves. The Istanbul exchange — measured honestly, total return, deflated by CPI — turned one lira of 2013 purchasing power into about 1.3×, with a −46% real drawdown along the way and one year, 2018, that destroyed a third of real wealth in twelve months. The classic retail compromise, half deposits and half BIST, also ended near 1.3×. The one traditional answer that genuinely worked is the oldest one: gold, at 3.1×. Gold gets both the credit and a caveat in section 6.
The pattern across all of these choices: every single asset a Turkish saver can hold had at least one regime in which it destroyed real wealth at double-digit annual rates. Deposits in 2021–23. Dollars after 2023. Stocks in 2018. Even gold spent 2013–2015 down roughly 30 percent in real terms. Holding one asset means implicitly forecasting which regime comes next — and nobody, including professionals, has demonstrated they can do that.
3. Rules instead of forecasts
If regimes can’t be forecast, the honest alternative is a rule that reacts — late, mechanically, but reliably. The simplest family of such rules is momentum: hold what has recently been working; drop what hasn’t. It is a humble idea. It doesn’t know why the lira is collapsing or why the central bank pivoted. It only knows what prices did over the last few months, and it acts on that and nothing else.
The specific rule I test is Gary Antonacci’s dual momentum, in the weekly implementation Quantpedia published in May 2026. It works like this. Every Wednesday, take each asset on a fixed list — stocks, bonds, gold, deposits; the exact Turkish list comes in the next section — and ask one question about it: how much has its price changed over the past ten weeks? Rank the assets by that number, buy the three at the top, and put one-third of the portfolio in each. Then repeat the whole exercise asking about the past twenty-five weeks instead of ten, and split the money equally between the two answers — half the portfolio follows the faster ten-week ranking, half the slower twenty-five-week one. That is the entire strategy. It contains three numbers — ten, twenty-five, and three — all inherited from the published source rather than tuned to Turkish data, and all frozen before any backtest ran.¹ There is one more ingredient, the absolute filter — a selected asset must also have been rising in its own right, or its slot retreats to safety — which sounds like a minor detail and turns out to carry an entire lesson (section 6).
4. Building the Turkish saver’s version
The list is the ten dollar-side building blocks a Turkish investor can hold at any decent broker — short and medium US Treasuries, gold, energy equities, the S&P 500, the Nasdaq, developed and emerging market indices, China, India, each entering the list only when its ETF actually existed — plus the two local assets that define the Turkish debate: the rolled TL deposit and the BIST-100, dividends included. Twelve assets in all.
Two design decisions matter more than the asset list.
First, all momentum signals are computed in nominal lira. Every dollar asset is converted at that Wednesday’s exchange rate before its momentum is measured. This is not a technicality: for a saver whose life is in lira, a dollar asset that is flat in New York but up 40% in lira is a rising asset — the currency is most of the signal, not noise contaminating it.
Second, this investor has no risk-free asset, so the strategy cannot “go to cash” — there is no cash that is safe. The TL deposit carries devaluation risk; the dollar carries domestic-inflation risk in regimes like today’s. When the absolute filter pulls a slot out of a falling asset, that slot goes to whichever of the two — deposits or dollars — has the stronger recent momentum. The deposits-or-dollars decision is made every Wednesday, by the rule.
Everything is net of a 10-basis-point cost per trade, and every result below is reported in real TL — deflated by official CPI — because that is the only honest scoreboard. Lira-nominal numbers flatter everything (the deposit account “never has a down week” while losing half its value); dollar numbers answer a different investor’s question.
5. What happened
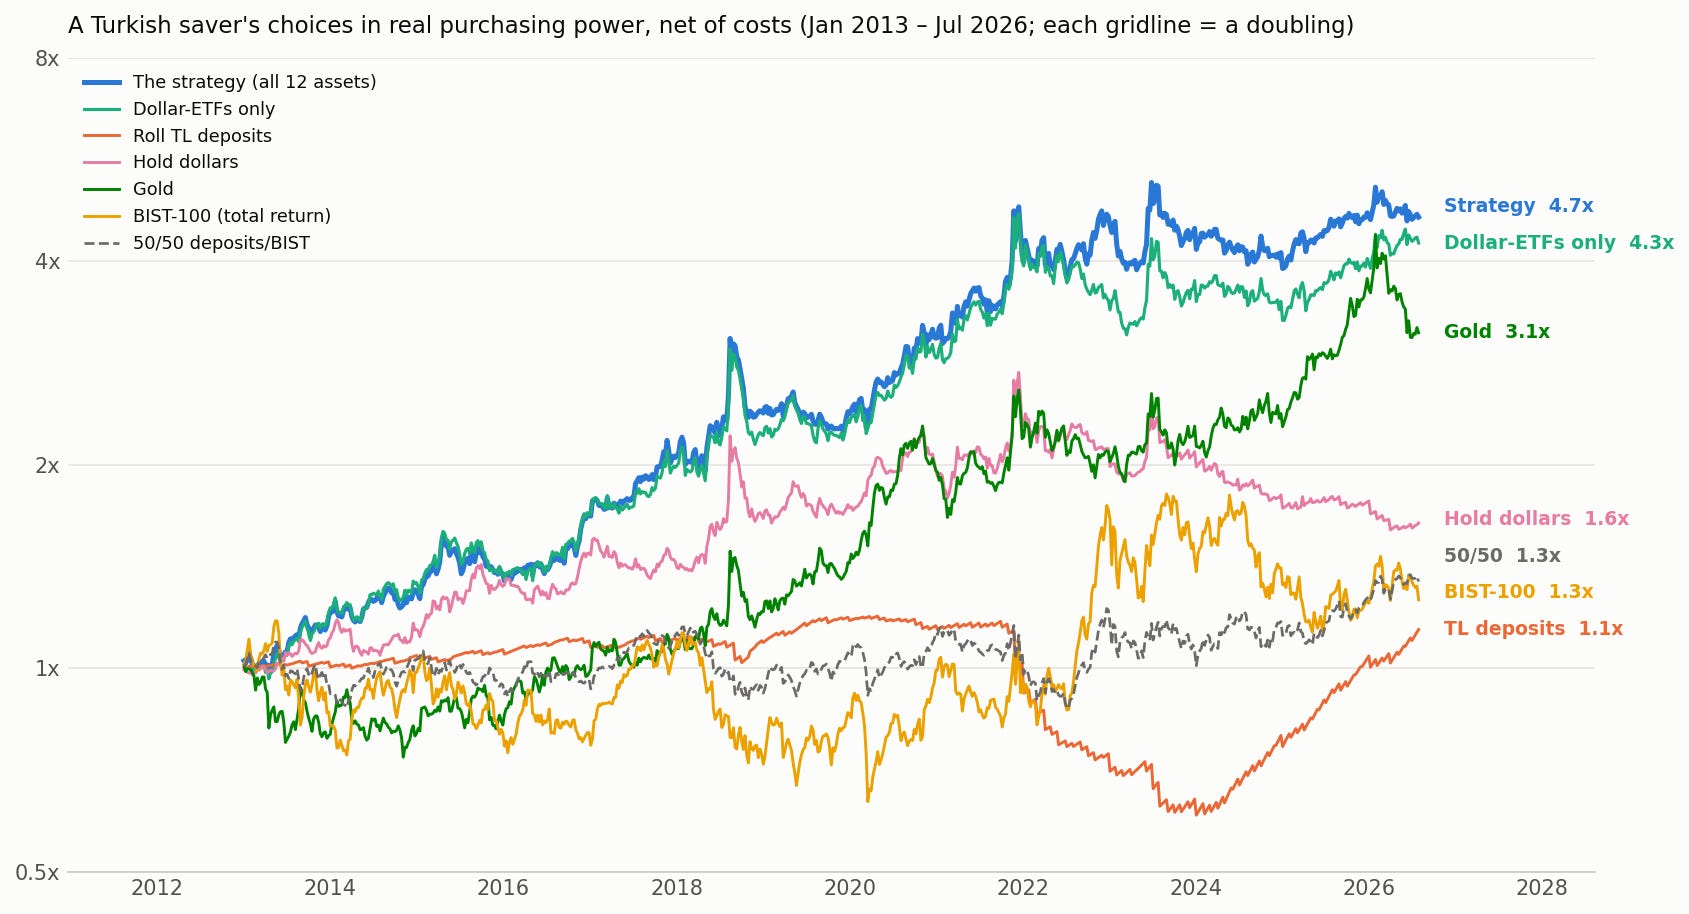
The rule turned one lira of January-2013 purchasing power into 4.7×, net of costs — 11.7 percent per year in real terms, through a currency crisis, an inflation surge, and a policy reversal. Against the two traditional answers the margin is not subtle: about 11½ points per year over rolling deposits, and 8 over holding dollars. Those two margins are large enough that they are very unlikely to be luck.² That distinction is worth naming now, because most of the other differences in this study are not — and the next section says so explicitly.
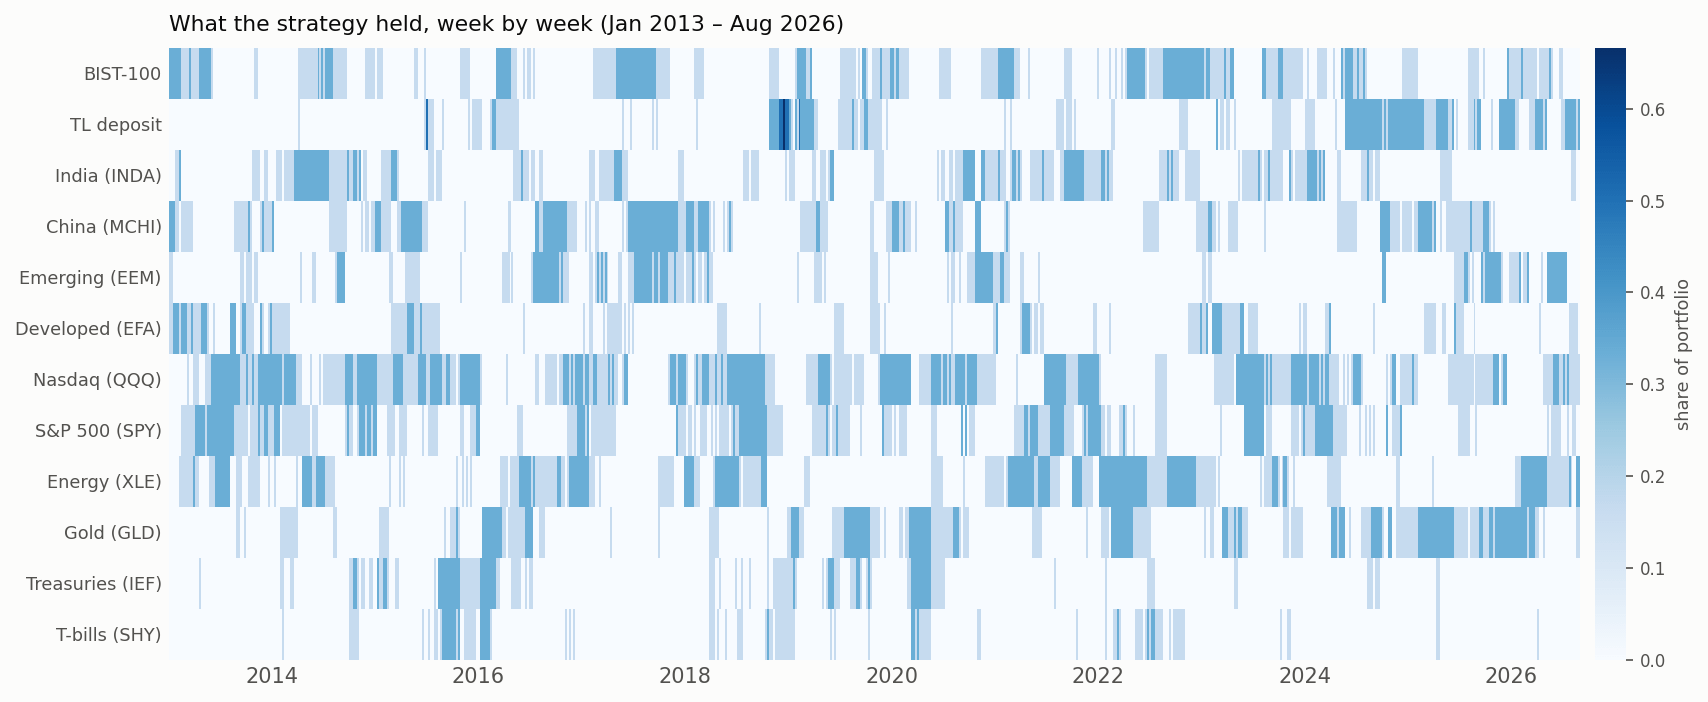
The final multiple matters less than how it was earned — what the strategy was doing while each single-asset answer was failing. In 2018, while BIST lost a third of its real value, the strategy gained 16 percent — it had rotated toward dollar assets as the lira slid. In 2021–23, while deposit-holders lost 17 percent of purchasing power per year, it compounded at +23 — it simply wasn’t there; it was mostly in energy stocks, in Istanbul equities through their enormous 2022 rally, and in Indian and US indices. The holdings chart (Figure 3) shows how: continuous rotation, with no permanent commitment to any asset — energy in 2022, gold through 2024–25, deposits finally appearing in size after 2023.
6. What the strategy did not do
This is the section most backtest write-ups omit, and it contains the three most interesting findings.
Most of the edge is diversification and discipline, not clever timing. An equal-weight portfolio of the same twelve assets, rebalanced weekly with no momentum at all, earned 9.2 percent per year real — about 3.3×. The momentum layer added perhaps 2½ points a year on top, and that increment is not statistically separable from luck. What the data supports saying is: holding all twelve assets under rules beat every single thing Turks actually do. What it does not support saying is that the timing layer is proven alpha.
Gold alone nearly matched the full strategy. 8.7 percent per year real, no rules, no broker, no rebalancing. Before concluding that the traditional answer was right all along, two caveats. We know gold was the winning single asset only in hindsight — choosing it ex ante is precisely the regime forecast the whole exercise refuses to make, and the same hindsight in 2013 would have picked something that then failed. And gold’s own path included three opening years down about 30 percent real — a gold-only saver in 2015 was in the same position as the deposit-holder in 2022: years in, deeply underwater in purchasing power. Still, the honest sentence must be written: in this sample, gold came close enough to the strategy that the difference could be luck.
The current regime exposed a real, structural limitation. Since mid-2023, rolling deposits has been the best trade in the country — rates near 50 against inflation falling through 40 meant roughly +18 percent per year in real terms. The strategy earned approximately zero real over the same period. Not because it couldn’t see deposits — it held them — but for two mechanical reasons worth understanding. First, the absolute filter asks “is it going up?”, and in a 42-percent-inflation world everything is going up; a Nasdaq position rising 35 percent in lira passes every test while quietly losing purchasing power. The filter Antonacci actually specified — beat the risk-free rate, not zero — repairs about half the shortfall: when rates are held high against inflation, as they have been since 2023, the deposit rate is, in effect, a live inflation hurdle.³ Second, and unfixable by any signal: with three equal slots, no asset can ever exceed one-third of the portfolio — and in every single week of this regime, the deposit sleeve sat at exactly its 33 percent ceiling. Diversification is a cap by construction. The same cap that saved the saver in 2018 and 2021 — no single bad answer could sink the portfolio — forbids concentration in the one period when a single answer was entirely right. The cap is the price of the diversification; this was the regime in which that price came due.
7. Can you actually run this?
The full version cannot be automated today: TL time deposits live at banks, with maturities, and no brokerage API rotates them weekly. So I ran the implementable subset — the ten dollar-side ETFs only, one broker, fully automatable — and it captured most of the result: 4.3× real. The gap between the two versions, which is what deposit access is worth to a Turkish investor, turns out to be genuinely unmeasurable from one country’s thirteen years — the two portfolios are 96 percent correlated, and the difference drowns in noise. The point estimates hint that the deposit layer’s value is small on average and concentrated in crisis years, which is what theory predicts of insurance; confirming that requires running the same engine on Argentina, Brazil, Egypt — which is the follow-on work, and the reason the engine was built country-agnostic.
There is a practical bridge worth naming: brokerage accounts that pay deposit-like yield on idle TL balances already exist in Turkey. A platform holding such balances can automate the full twelve-asset version — slowly, monthly rather than weekly — which is roughly what disciplined Turkish savers do by hand anyway.
8. What this proves, and what it doesn’t
It does not prove momentum timing works — see section 6. It ignores taxes. Those are not a simple haircut here: foreign-ETF gains must be self-declared and are measured in lira (an inflation-indexation rule offsets part, but not necessarily all, of pure devaluation), while deposit interest is taxed at source — so taxes fall differently on each strategy being compared. That deserves its own essay and professional advice; nothing here is tax guidance. It is one country’s single history. Its costs assumption matters: at 10 basis points per trade the strategy clears everything; at 25 — closer to what retail actually pays once spreads and FX conversion are counted — it still beats every naive option, but a third of the real return is gone. And its rules are, by construction, late: a weekly signal with a 10-to-25-week memory needed most of 2021’s six-week collapse to react. The strategy does not avoid crises; it exits early enough that they are survivable. That is a more modest promise.
What it does prove is narrower and, I think, more useful. A Turkish saver did not need forecasts, hot tips, or a view on the central bank. Holding all of it — dollars and deposits and gold and stocks — under mechanical rules, measured honestly in purchasing power, turned thirteen catastrophic years into 4.7×, while every single-asset answer the culture argues about went roughly nowhere. The answer to faiz mi, dolar mı is that it is the wrong question. The useful product — one no Turkish platform currently offers — holds all of these assets at once, rotates them by rules, and reports the balance in purchasing power, not in lira: a deposit account that never shows a down week while losing half its real value is a reporting problem as much as an investment one.
Notes
¹ Methods and pre-registration. The asset list, the strategy’s three parameters (the two momentum lookbacks of 10 and 25 weeks, and the choice of holding the top three assets), the weekly Wednesday rebalance, cost assumptions, and reporting conventions were all fixed in a written spec before any backtest ran; the engine was first validated against Quantpedia’s published 9-ETF result (Sharpe ≈ 0.89 vs their ≈ 0.9) before any Turkish data entered. Every rule change tried after seeing results is labeled as such in the study repository, with dates. Data: US ETF prices are dividend-adjusted closes from Yahoo Finance. Everything Turkish comes from the central bank’s public EVDS database: the average rate banks paid each week on newly opened TL deposits of up to three months’ maturity (in practice mostly the standard one-month account) (the rate our deposit sleeve rolls at — the flow rate, what a new depositor actually got, not the average of old accounts; accrued with weekly compounding, which slightly flatters the deposit strategy at high rates); the official USDTRY exchange rate; the BIST-100 total-return index, dividends included; and the official consumer price index, used to state every result in purchasing-power terms. Real-TL series end at the last published CPI month. Exact series codes and the full data pipeline are in the study repository.
² On “unlikely to be luck.” The phrase can be made precise with a t-statistic: it measures how large the average weekly return difference between two portfolios is, relative to how noisy that difference is, with values above roughly 2 conventionally treated as unlikely to be chance. Over the full period, the strategy’s margin over rolling deposits scores about 2.4 and its margin over holding dollars about 2.2 — both clear the bar. The margins that do not clear it are the strategy’s edge over the equal-weight portfolio (about 1.1), its edge over gold alone (about 0.5), and every claim about which regimes the full version beats the dollar-only version in. Wherever a difference fails this test, the essay calls it unproven rather than claiming it. Two caveats about the test itself, in opposite directions: these are simple t-tests, and financial returns have fatter tails than the test assumes, so the true uncertainty is somewhat larger than stated; and failing the test is not proof of no effect — thirteen years is simply too short a sample to measure a difference of a few percent a year between two highly similar portfolios.
³ The risk-free hurdle variant. Replacing “momentum > 0” with “momentum > deposit-sleeve momentum” (Antonacci’s original excess-over-risk-free definition, applied with deposits as this investor’s reference rate) raises the full-period result from 11.7 to 12.1 percent per year real and roughly halves the post-2023 shortfall, at a cost of a fraction of a point in earlier years. It was conceived after seeing the post-2023 result and is therefore reported as a robustness variant, not the headline. Details, code, and the full audit trail: study repository.
A note on authorship. This study was built in collaboration with an AI assistant (Anthropic’s Claude), which implemented the engine and drafted the prose under my direction. The design, the pre-registered spec, and the editorial and analytical judgments are mine — the dated log in the repository records who did what.
Code, data pipeline, results, and the pre-registration audit trail: github.com/chitown2016/dual-momentum-turkey
This came out just when I was playing with Antonacci’s dual momentum “what if” cases. Interesting angle! Every dinner table, every coffee break somehow discussed this with opinions in Turkey, thanks for the numbers.